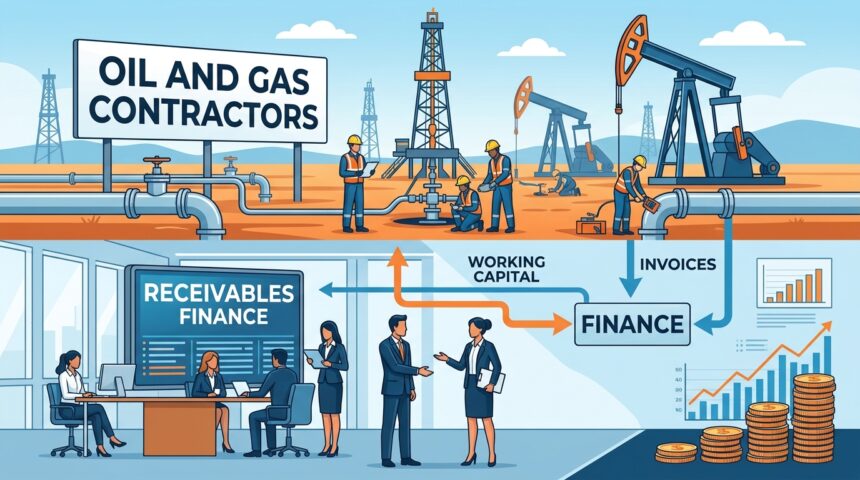
Oil and gas contractors can face long payment cycles even after delivering a service. Receivables finance may release cash from approved invoices, but eligibility depends on the underlying contract and the status of each claim.
Separate earned revenue from expected revenue
A signed work order is not the same as an accepted invoice. Lenders will distinguish unbilled work, milestone claims, certified amounts and invoices already approved for payment. The further a claim is from unconditional acceptance, the harder it may be to finance.
Read the contract
Payment may be subject to back charges, performance claims, retention or broad setoff. Assignment restrictions and notice requirements can also affect the structure. The lender needs to know whether the debtor may reduce or delay the amount shown on an invoice.
Measure debtor concentration
A contractor may have dozens of invoices but only one large customer. That concentration influences advance rates and limits. Payment history and the debtor’s credit standing matter alongside the contractor’s own financial results.
Control collections
A facility can use a designated account and regular debtor reporting so collections reduce the outstanding balance. The process should fit the customer’s payment systems and clearly identify which invoices have been sold, assigned or pledged.
Define the financed claim
An oilfield services company may record revenue while waiting for a customer’s approval process. The lender needs to know whether the work has been completed, certified and invoiced. A timesheet, signed field ticket, milestone certificate and approved invoice provide different levels of evidence. Identify which one creates a payable obligation under the contract. A borrowing request built on work in progress should not be described as ordinary invoice finance without explaining the performance risk it carries.
Read acceptance provisions
Some contracts permit the customer to reject a service ticket within a specified period or require further technical signoff before payment. Others allow broad back charges for delays or equipment failures. These rights can reduce the amount collectible from an invoice. The lender may set eligibility only after formal acceptance or reserve against historical deductions. Contractors should document the normal approval timeline and actual experience, including how often invoiced amounts are amended after submission.
Address retention and setoff
A customer may withhold a percentage of each invoice until project completion or net unrelated claims against an amount due. Even where the customer is financially strong, these terms affect the value of assigned receivables. Separate retention from the immediately payable balance in the borrowing base. Review whether assignment is permitted and whether debtor notice or acknowledgment is required. Local counsel may need to advise on enforceability, particularly when the contract, customer and contractor sit in different jurisdictions.
Analyze concentration honestly
A contractor serving one major operator may have attractive invoices and still face concentration risk. A project suspension, payment system change or dispute can affect most receivables at once. Show customer-level aging and historical collections, not just total revenue. A lender may impose a cap on eligible invoices from one debtor or reduce its advance rate. The contractor should forecast available funding after those limits, especially during large projects when outstanding invoices rise quickly.
Reconcile invoices to cash
A useful data set traces the work order to performance evidence, approved invoice and bank receipt. Explain credit notes, deductions and overdue accounts. If customers pay through a common remittance account, the financing arrangement should identify relevant collections without disrupting other business. Monthly aging reports must use consistent invoice dates and customer names. Reconciliation exposes whether payment delays arise from ordinary processing, documentation gaps or disputed work.
Model the period before billing
Receivables finance releases cash only when invoices become eligible. Contractors may need to pay crews, fuel and subcontractors weeks before they can bill. That earlier gap could require a separate working capital line or additional company liquidity. Show both gaps on a cash calendar. Using an invoice facility to justify funding unperformed work creates a mismatch unless the lender expressly structures and prices that risk.
Plan for project changes
Variations are common in field services, but an unsigned change order may not become an enforceable receivable. Track original contract value, approved variations, pending claims and deductions separately. A lender may exclude disputed variation invoices until customer approval. The contractor should also identify what happens when equipment demobilizes or a project is suspended. A facility built around a specific customer needs a process for adding eligible work from new projects.
Compare term sheets on eligibility
Pricing matters, but the usable amount depends on which invoices qualify, concentration caps, reserves and collection procedures. Ask when an invoice becomes eligible and when it ages out. Test the proposed formula against actual invoice data for several months. A line with a higher stated limit may provide less cash than expected if approval lags and retention are substantial. The operating burden of daily reporting and debtor notices should also be reflected in the decision.
Maintain an invoice exception log
For each invoice excluded from finance, record the reason: missing approval, unresolved variation, retention, dispute, age or a concentration cap. Assign an owner to obtain the missing certificate or resolve the issue with the customer. This log helps management distinguish a temporary paperwork problem from a recurring contract feature that reduces financing capacity. It also supports more accurate cash forecasting. If the same customer routinely approves invoices six weeks after field work ends, the business should model that delay instead of expecting a new finance provider to make it disappear. A reliable facility is based on the amount and timing of invoices that actually qualify, rather than gross billings shown in an accounting system.
The practical test is whether the proposed facility still works when a shipment runs late, a document needs correction or a buyer pays after the expected date. Record those assumptions, assign responsibility for monitoring them and discuss the response with prospective financing parties before execution.
Fund a defined asset
Oil and gas contractor receivables finance is most credible when the invoices are identifiable, accepted and collectible. It should not be presented as a way to finance uncertain future awards or unresolved contract disputes. Those needs call for separate analysis.